Should I overpay my mortgage?

If you’re a homeowner, you might wonder whether it’s a good idea to pay more towards your mortgage each month.


What does overpaying your mortgage mean?

Overpaying simply means paying more than your required monthly mortgage payment. You can do this by making one-off payments or by paying more off each month.   

Overpaying reduces your mortgage balance, so you pay less interest in the long run.  You may also be able to reduce your term.

It can save you money in the long run, but it’s not the best choice for everyone . Let’s look at the benefits, things to consider , and some alternatives to help you decide if overpaying your mortgage is right for you.

Is overpaying right for you?

Benefits of overpaying

  • Save money on interest - overpaying reduces your mortgage balance, meaning you pay less interest over time. 
  • Lower LTV - if you overpay then you’ll lower your loan-to-value ratio. This could help you access better rates if you get a new mortgage deal.
  • Enjoy greater returns than savings – overpaying can often help you save more in interest than you would earn from putting your money into a regular savings account.

Things to consider

  • Early Repayment Charges (ERCs) - some mortgages have limits on how much you can overpay each year without paying a fee. 
  • Less flexibility - money used for overpayments can’t easily be withdrawn if you suddenly need it . You also can’t get a refund on overpayments.
  • Other debts might cost more - if you have other debts, like credit cards or loans, with higher interest rates, it may be better to pay those off first.

How overpaying your mortgage works - an example

Let’s say you have a £200,000 mortgage with 25 years left and an interest rate of 5% that stays the same for the whole term. Your monthly payment is about £1,055, which will continue at that level until the mortgage is paid.

Impact of lump sum overpayments

Lump sum

Reduction in term

Interest saved

Lump sum

£1,000

Reduction in term

2 months

Interest saved

£1,706

Lump sum

£5,000

Reduction in term

1 year, 2 months

Interest saved

£8,308

Lump sum

£10,000

Reduction in term

2 years, 4 months

Interest saved

£16,080

Impact of regular monthly overpayments

Monthly overpayment

Reduction in term

Interest saved

Monthly overpayment

£50

Reduction in term

1 year, 10 months

Interest saved

£9,800

Monthly overpayment

£100

Reduction in term

3 years, 5 months

Interest saved

£18,020

Monthly overpayment

£200

Reduction in term

6 years

Interest saved

£31,067

You would have to make regular overpayments every month for the whole term to save this much interest.

Remember, these numbers are just an example and a rough guide, not exact figures. Your savings will depend on your interest rate, how much you overpay, and your lender’s rules. Your term won’t automatically shorten. You may have to speak to your lender to arrange this.

If you’re a Lloyds mortgage customer, you can log in to use our mortgage overpayment calculator.

How overpaying saves interest

What happens after I overpay?

When you make overpayments, you can:

  • lower your monthly payments while keeping the same term
  • keep your monthly payments similar and shorten your mortgage term, although you may have to speak to your lender if you want to do this.

At certain times, your lender might work your payments out again so they're lower.  But you won’t be mortgage-free sooner.

Did you know?

Interest is worked out daily. This means that the earlier in the month you  overpay, the more you can save on interest.

Your mortgage in your pocket


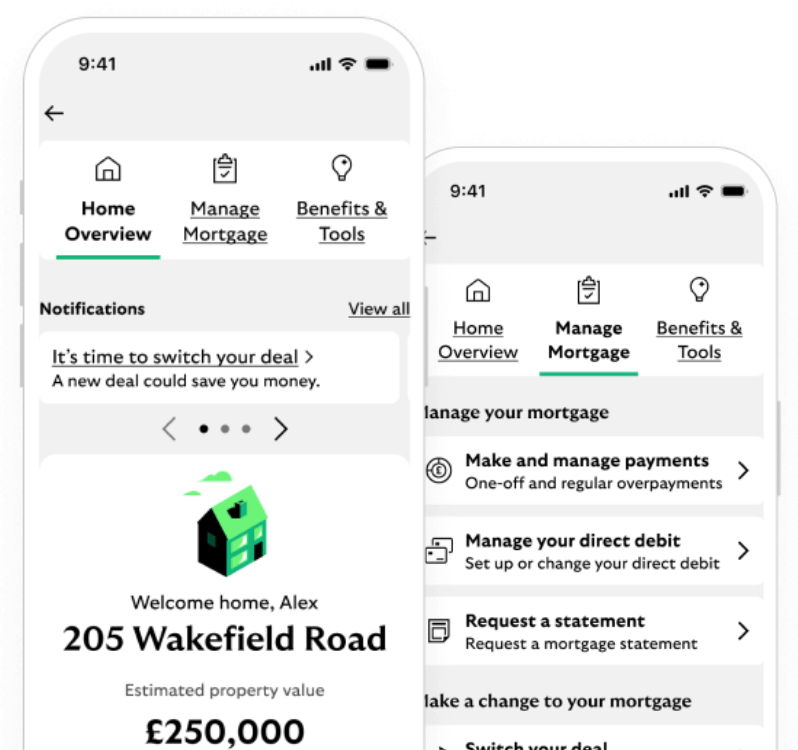
Get Home Wise

  • Manage your payments.
  • Set up regular overpayments.
  • Use the overpayment calculator.

And much more, all online. Join the community of customers managing their mortgage at the touch of a button.

Discover Home Wise

Let’s look at the details

  • You can overpay your mortgage by as much as you’d like. You can even pay it all off. Most mortgage deals will have an overpayment limit – if you pay off more than the limit, then you may have to pay ERCs.

    You can usually overpay your mortgage by up to 10% of your year-start balance . Any more than that and you may have to pay ERCs. Check the details of your mortgage for more information about ERCs.

    Tracker mortgages and those on standard variable rates (SVR) may let you overpay without ERCs. Always check the details of your mortgage deal.

  • With an interest-only mortgage, your monthly repayment covers the interest you are charged for the mortgage loan.

    The value of your mortgage must then be paid in full at the end of the term.

    When you overpay, you’re paying extra money towards the capital (the amount borrowed), even though your monthly payments normally don’t do that.

    Overpaying does 2 things

    • Lowers your outstanding balance, so you’ll owe less at the end of the term.
    • Helps you pay less interest overall, as interest is charged on a smaller balance.

    Switching some or all of your interest-only mortgage to a repayment mortgage could save you even more interest over the term.

  • There are 2 ways you can overpay your mortgage.

    You can also overpay to pay off your mortgage in full.

Other things to do with your money

If you can comfortably afford your mortgage payments, then there are some other things you can do with your money.

Saving

Consider saving money in a separate account for emergencies before making overpayments. Saving might also be a better option if the interest rate is higher than your mortgage rate.

See our savings accounts

Pay off higher-interest debts

Clearing debts with higher interest rates than your mortgage will usually save you more money.

Reducing debts

Investing

You might get better returns by investing your spare cash. But remember that investments can go down as well as up.

Explore investing

You may also like

Eco home offers

We love rewarding our customers for choosing more sustainable options for their homes. Terms and conditions apply.

Discover eco home offers

Mortgage help and guidance

Use our help hub to discover everything you need to know about mortgages.

Find help and guidance

Homeowner inspiration

We’ve brought together inspirational content, hints, tips and tools for homeowners like you.

Find inspiration

Make changes to your mortgage

Learn about the changes you can make to your mortgage and how to get started.

Make changes to your mortgage

Make changes to your mortgage

Learn about the changes you can make to your mortgage and how to get started.

Make changes to your mortgage