Set up a regular overpayment
A regular overpayment is where you pay more each month than your required monthly payment amount.
You can do this online
- Regular overpayments will reduce your mortgage balance and save you interest.
- Make overpayments to your mortgage at any time.
- It's easy to set up and manage in our app or online banking.
You can’t get a refund on any overpayments you make.
Steps to take
We'll guide you through it.
-
You can easily set up a regular overpayment by direct debit in our app or online banking.
Log in and select your mortgage, then Home Wise. On the 'Mortgage' tab, select 'Make and manage payments', then 'Amend or cancel an overpayment.'
Once complete, we’ll send you a letter to confirm your arrangement.
If you don't bank online, you’ll need to call us to adjust your direct debit.
-
You can easily set up a regular overpayment by standing order in our app or online banking.
Log in and select your mortgage, then Home Wise. On the 'Mortgage' tab, select 'Make and manage payments', then 'Amend or cancel an overpayment.'
To make regular overpayments by standing order from another bank, you’ll need these details:
- sort code: 30-00-00
- account number: 00353019
- account name: Lloyds Bank plc.
For the payment reference, input your mortgage account number, plus an extra ‘00’ on the end, so it’s 16-digits in total.
To make an overpayment to a sub account, replace ‘00’ with the 2-digit sub account number instead. For example ‘02’. Visit How do I apply my overpayment to a specific sub account? for more information.
Getting started online
Let’s look at the details
-
-
-
You can choose one of these options:
Standard arrangement
Fixed arrangement
Standard arrangement
With this kind of arrangement, you can choose the amount you’d like to overpay by each month. This will then be collected on top of your normal monthly payment.
For example, if your normal monthly payment is £400 and you choose to make a regular overpayment of £100, you’ll pay £500 in total. If your normal monthly payment changes to £500, you’ll pay £600 each month.
The total amount you have to pay each month can vary, so it’s worth considering if this option is right for you.
You’ll need to call us to apply overpayments to a specific sub account.
When choosing a sub account, it’s worth thinking about its term, balance, interest rates, ERCs, and any other fees or charges that might apply.
Your overpayments will continue until you tell us you’d like to stop or change your arrangement.
Fixed arrangement
This option allows you to choose a fixed amount to pay each month. This must be more than your normal monthly payment.
For example, if your normal monthly payment is £400, you can fix it at £500, meaning you’ll make a regular overpayment of £100. If your normal monthly payment changes to £350, your overpayment will automatically adjust to £150.
You’ll need to call us to set this up .
You can’t apply your overpayments to a specific sub account with this kind of arrangement.
Your overpayments will continue until you tell us you’d like to stop or change your arrangement. But if your normal monthly payment goes above your fixed amount, we’ll cancel it.
-
If you set up your overpayments by direct debit
We’ll take your new monthly payment amount on your next due date. If your mortgage payment is due in the next 7 days, we might not have enough time to update the amount. This means your new monthly payment will start the following month.
If you set up your overpayments by standing order
Standing orders are only sent on working days. Allow up to 3 working days for your payments to reach us and appear on your balance. You won’t get any confirmation this has been received.
-
You can choose a sub account to overpay when you pay in our app or online banking.
If not, then we will apply your extra payment across all parts of your mortgage like your normal monthly payment. You can check your sub accounts online or on your annual statement.
Keep in mind, some mortgages have an early repayment charge if you overpay more than 10% of your balance in a calendar year.
Information about sub accounts
Your mortgage may be a combination of different repayment methods with different interest rates over different mortgage terms. If so, your mortgage will be split into multiple parts called sub accounts. Most customers will have a sub account 01, which is their main mortgage and a sub account 99 which holds fees. Some customers, may also have a sub account 98 if they have a mortgage account fee.
Each sub account has a separate monthly payment that we total before collecting the full amount from you each month. When we receive your total monthly payment, we split it and give each sub account the amount it needs to ensure you repay your interest charges for that month.
For repayment sub accounts, each month, your payments go towards reducing the amount you owe as well as paying off the interest.
For interest-only sub accounts, the balance doesn't reduce as you're only paying back the interest and it's a requirement that you have a repayment plan in place. Find out more about the different ways of repaying your mortgage.
Worked example
If your mortgage has 2 sub accounts and your total monthly payment is £400, of which:
- £100 is the monthly payment on sub account 01
- £300 is the monthly payment on sub account 02.
We calculate what percentage of your total monthly payment is made to each sub account as follows.
- Payment on sub account 01 £100 / £400 x 100 = 25%
- Payment on sub account 02 £300 / £400 x 100 = 75%
If you overpay £100 on top of your regular monthly payment, we'll apply £25 of the overpayment to sub account 01 and £75 to sub account 02. That's 25% to sub account 01 and 75% to sub account 02.
Your mortgage in your pocket
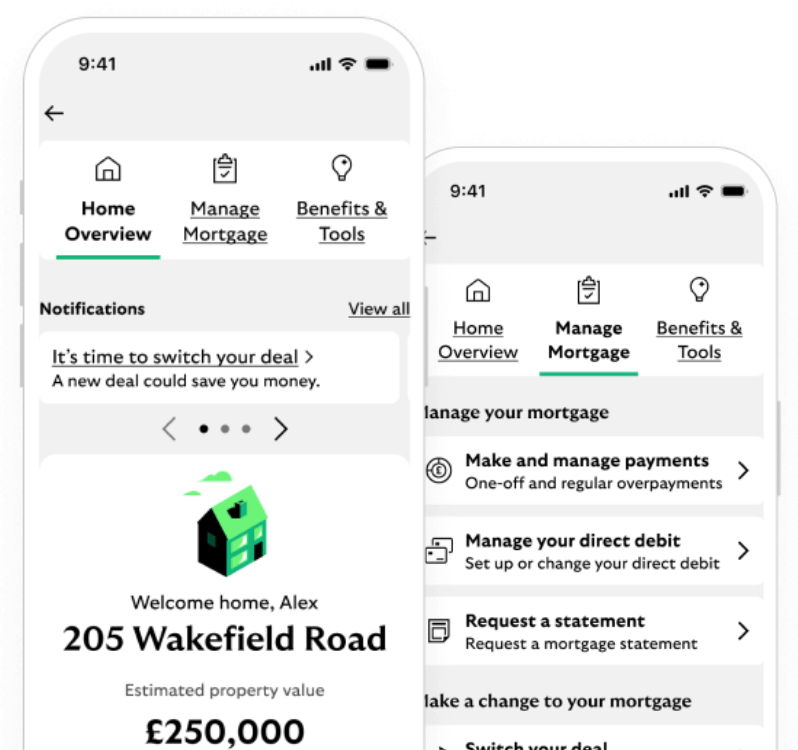
Get Home Wise
- Manage your payments.
- Set up regular overpayments.
- Use the overpayment calculator.
And much more, all online. Join the community of customers managing their mortgage at the touch of a button.
You may also like